
If you own a French Bulldog, pet insurance for a French Bulldog isn’t optional budgeting — it’s the single smartest financial move you can make as a Frenchie owner. Frenchies are wonderful dogs and among the most expensive breeds on earth to keep healthy. This guide covers what French Bulldog insurance typically costs in 2026, why the breed is priced the way it is, what your policy absolutely must cover, and six practical tips to lower your premium.
Educational only — not financial advice. Premiums below are typical market ranges; always compare live quotes for your dog’s age and your ZIP code.
Why French Bulldogs Cost More to Insure
Insurers don’t charge Frenchies more out of spite — they charge more because French Bulldogs generate more, and more expensive, claims than almost any other popular breed. The reasons are anatomical:
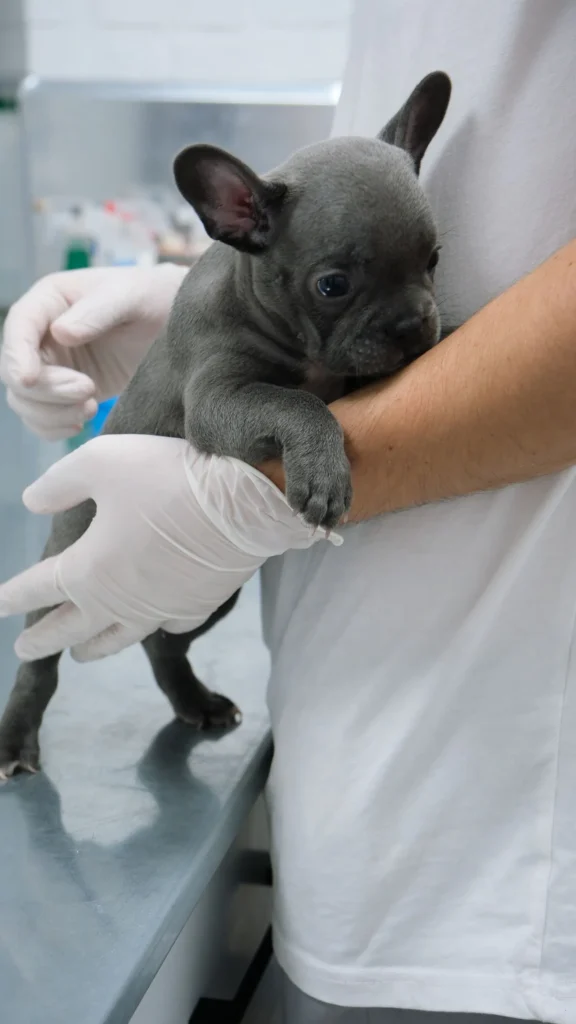
Brachycephalic airway syndrome (BOAS). That adorable flat face means narrowed nostrils, an elongated soft palate, and a narrow trachea. Many Frenchies need airway surgery at some point — and it’s a multi-thousand-dollar procedure. This single factor drives a large share of Frenchie premiums.
Spinal issues. French Bulldogs are prone to hemivertebrae (misshapen vertebrae) and intervertebral disc disease. Spinal surgery is among the most expensive procedures in veterinary medicine.
Skin and allergies. Those charming wrinkles trap moisture and breed infections; Frenchies also rank high for environmental and food allergies, which mean years of ongoing claims — exactly what insurers price for.
Eyes, ears, and heat. Cherry eye, corneal ulcers, chronic ear infections, and dangerous heat intolerance round out a breed health profile that keeps actuaries busy. None of this means you shouldn’t own a Frenchie — it means you should insure yours early, before any of it is documented in a vet record.
What Pet Insurance for a French Bulldog Typically Costs
For a young, healthy French Bulldog, comprehensive accident-and-illness coverage commonly runs $70–$120+ per month — roughly double the $30–$70/month typical for an average mixed-breed dog. Puppies trend toward the lower end of the Frenchie range; a 6-year-old Frenchie with any vet history can exceed it significantly.
Three things push individual quotes around within (and beyond) that range:
Age at enrollment matters more for Frenchies than for most breeds. Because breed-related conditions develop young and get documented fast, every month you wait risks turning a future claim into a pre-existing exclusion. A Frenchie enrolled at 10 weeks is a fundamentally cheaper risk than the same dog enrolled at 3 years.
Your plan settings still apply. The standard levers — deductible ($250–$1,000 typical), reimbursement rate (70–90%), annual limit ($5,000 to unlimited) — work the same way. Our deductible guide walks through the tradeoffs with worked examples.
Location swings the number hard. Specialist surgery costs (and therefore premiums) in major metro areas can run 40–60% above rural ZIP codes. Get quotes for your actual address, not a national average.
What Your Frenchie Policy Must Cover
Not all policies treat French Bulldogs equally. Before you buy, verify these four things in writing:
1. Hereditary and congenital conditions are covered — with no per-condition sub-limits. This is the big one. BOAS, hemivertebrae, and disc disease are hereditary. Some budget plans exclude hereditary conditions outright or cap them at a few thousand dollars — which makes the policy nearly useless for a Frenchie. If hereditary coverage isn’t explicit, keep shopping.
2. No bilateral exclusions that gut orthopedic coverage. Some policies exclude a condition on both sides of the body if it appeared on one side pre-enrollment. For a breed prone to bilateral issues, read this clause carefully.
3. Reasonable orthopedic waiting periods. Many insurers impose extended waiting periods (6–12 months) for cruciate and other orthopedic conditions. Shorter is better; some insurers reduce the wait with a clean vet exam at enrollment.
4. A high enough annual limit. With Frenchie surgery bills routinely running into the thousands, a $5,000 annual cap is thin. Given the breed’s risk profile, a $10,000+ or unlimited annual limit is worth serious consideration — price the difference before dismissing it.
The Lifetime Math for a Frenchie
Sticker shock fades when you run the lifetime numbers. Take a mid-range Frenchie premium of $90/month: over an 11-year lifespan, that’s roughly $11,880 in total premiums — before any reimbursements. Now stack that against what the breed actually generates: a single emergency surgery ($1,500–$7,000), a BOAS airway procedure (multi-thousand dollars), years of allergy management, or a spinal episode. One bad year can return several years of premiums; two bad years can return the lifetime total.
This is why the “Frenchies are too expensive to insure” logic runs backwards. The breeds that cost the most to insure are precisely the breeds where insurance pays off most often. The expensive premium is the signal — it tells you the risk is real.
6 Tips to Lower Your French Bulldog’s Premium
1. Enroll as a puppy — ideally before 12 weeks. This is the highest-value move on this list. Early enrollment locks in the lowest premium tier and, critically, gets coverage in place before the first vet note about noisy breathing or skin irritation becomes a pre-existing exclusion. Our puppy insurance cost guide explains the enrollment window in detail.
2. Choose a higher deductible you can actually cover. Moving from $250 to $750 can cut 25–40% off the premium. Only do this if you have the deductible amount in savings — a deductible you can’t pay is just an uncovered claim.
3. Consider 80% reimbursement instead of 90%. The monthly savings are real; the pain only shows on catastrophic bills. For young Frenchies, 80% is a reasonable middle ground.
4. Ask about multi-pet and annual-pay discounts. Multi-pet discounts typically run 5–10%, and annual payment can save another 5–10% over monthly billing. Stack them.
5. Keep your Frenchie lean and cool. This isn’t an insurance trick — it’s the two cheapest health interventions for the breed. Excess weight worsens breathing and joint stress; heat management prevents emergency vet visits. Fewer claims now won’t lower today’s premium, but a clean claims history keeps renewals manageable.
6. Compare at least three providers on the four coverage points above. For Frenchies, the cheapest quote with weak hereditary coverage is the most expensive policy you’ll ever buy. Compare coverage first, price second.
When to Enroll Your Frenchie
The honest answer: the day you bring them home. French Bulldogs develop documentable breed issues earlier than most breeds, and insurers’ pre-existing-condition rules are unforgiving — a vet’s casual note about “stenotic nares” or “mild skin irritation” at a puppy visit can follow your dog for life. Coverage typically starts after a short waiting period (often ~14 days for illness), so enrolling at 8–10 weeks means you’re protected through the highest-risk early months.
Adopting an adult Frenchie? Enroll immediately anyway — a clean slate going forward still beats no coverage, and many adult Frenchies go years between major claims. Just expect a higher premium and read the pre-existing terms with extra care.
For the full cost framework — deductibles, reimbursement math, and plan-type comparisons — see our complete 2026 pet insurance cost guide.
Frequently Asked Questions
How much is pet insurance for a French Bulldog per month?
For a young, healthy Frenchie, expect roughly $70–$120+/month for comprehensive coverage — about double the average dog. Age, location, and plan settings move the real number significantly.
Is pet insurance worth it for a French Bulldog?
More than for almost any other breed. Frenchies combine high claim frequency (breathing, skin, spine) with high claim severity (multi-thousand-dollar surgeries). One major surgery can exceed years of premiums.
Does pet insurance cover BOAS surgery?
It depends on the policy and timing. Plans that explicitly cover hereditary conditions will generally cover BOAS surgery if it wasn’t pre-existing at enrollment. Plans that exclude hereditary conditions won’t. Verify in writing before buying.
Can I insure an older French Bulldog?
Yes, but expect higher premiums and pre-existing exclusions for anything already in the vet record. It’s still worth quoting — future unrelated emergencies are still covered.
Do all insurers charge French Bulldogs more?
Nearly all of them price Frenchies well above the average dog — the breed’s claim data is consistent industry-wide. The difference between insurers is smaller than the difference between a good and bad policy choice, so prioritize the four coverage points above over chasing the lowest quote.
Petsofweb content is educational only and is not financial advice. Breed risk profiles and premiums change — compare live quotes from multiple providers before enrolling.
Leave a Comment